
Discovering a wet spot on your ceiling or hearing the ominous drip of a pipe can send any homeowner’s heart racing. It’s not just about the mess; it’s about the potential financial burden that comes with repairing structural damage and replacing ruined belongings. You are likely asking yourself the critical question: Are plumbing leaks typically covered by homeowners insurance? The answer is nuanced, depending heavily on whether the leak was sudden or gradual. In this guide, we will break down exactly what your policy likely covers, what it doesn’t, and how you can protect your home and wallet.
Understanding the “Sudden and Accidental” Rule
To understand your coverage, you must first grasp the fundamental principle that most US insurance carriers operate under: the distinction between sudden accidents and long-term wear and tear.
Most standard homeowners insurance policies (such as the ubiquitous HO-3 form) cover water damage if it is “sudden and accidental.” This means the event happened unexpectedly and was not the result of negligence or lack of maintenance.
What Qualifies as Sudden?
- A pipe bursts due to freezing temperatures overnight.
- A washing machine hose snaps while you are at work.
- A water heater ruptures without warning.
In these scenarios, the resulting water damage to your floors, walls, and personal property is typically covered. However, it is crucial to note that the insurance usually covers the damage caused by the water, not necessarily the cost to fix the leaking pipe itself.
Expert Insight: According to industry data, water damage is one of the most common home insurance claims, accounting for nearly 25% of all claims filed in the United States. Yet, a significant portion of these are denied due to misclassification of the cause.
The Major Exclusion: Gradual Damage and Neglect
If you are wondering, “Are plumbing leaks typically covered by homeowners insurance if they’ve been dripping for months?” the short answer is almost always no.
Insurance is designed to protect against unforeseen disasters, not to serve as a maintenance fund. If a leak develops slowly over time, it is considered “gradual damage.” Insurers argue that had the homeowner performed regular inspections and maintenance, the issue could have been caught and fixed before it caused significant harm.
Common Examples of Non-Covered Leaks:
- Slow Drips: A faucet or pipe joint that has been leaking slightly for weeks or months.
- Wear and Tear: Old pipes that corrode and fail due to age.
- Poor Maintenance: Failure to replace worn-out washing machine hoses or ignore known minor leaks.
| Feature | Sudden & Accidental Leak | Gradual/Negligent Leak |
|---|---|---|
| Onset | Immediate, unexpected | Slow, develops over time |
| Cause | Burst pipe, appliance failure | Corrosion, loose joints, age |
| Coverage Status | Typically Covered | Typically Excluded |
| Example | Pipe freezes and bursts | Slow drip under sink rots cabinet |
For more detailed definitions of property damage terms, you can refer to general insurance principles outlined on Wikipedia.
Specific Scenarios: What Is and Isn’t Covered
Let’s dive deeper into specific plumbing situations to clarify gray areas.
1. Burst Pipes Due to Freezing
If you live in a colder climate, frozen pipes are a major risk. If a pipe bursts because you were away and the heat was turned off, your insurer might deny the claim citing negligence. However, if you maintained a reasonable temperature and the pipe burst despite your best efforts, the resulting water damage is generally covered.
2. Slab Leaks
Slab leaks occur when pipes beneath your concrete foundation break. These are tricky. If the leak was sudden (e.g., a construction accident hit the pipe), it might be covered. However, because slab leaks are often caused by soil shifting or corrosion over years, they are frequently classified as maintenance issues. Check your policy for specific “slab leak” endorsements.
3. Sewer Backups
Standard policies rarely cover water that backs up from sewers or drains. This requires a separate endorsement or rider. If your toilet overflows due to a main line blockage, standard insurance won’t pay unless you have this specific add-on.
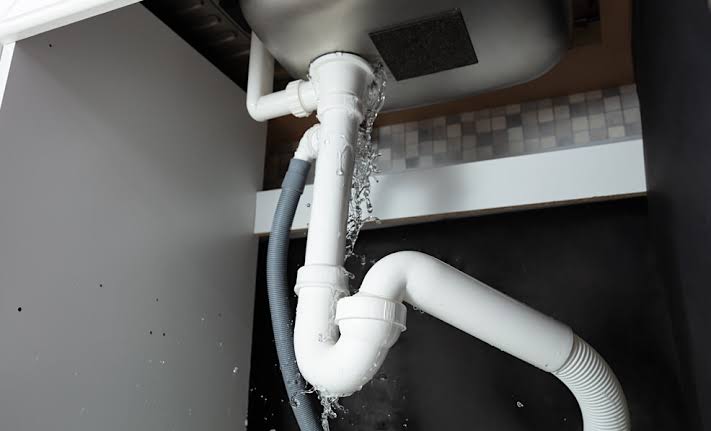
How to File a Claim for a Plumbing Leak
If you determine your leak is covered, acting quickly is vital. Follow these steps to ensure a smooth claims process:
- Stop the Water Source: Immediately shut off the main water valve to prevent further damage. Mitigation is your responsibility.
- Document Everything: Take high-resolution photos and videos of the leak, the source, and all damaged items. Do not throw anything away until the adjuster sees it.
- Make Temporary Repairs: Use tarps or buckets to minimize damage. Keep receipts for any materials bought for these emergency fixes; they may be reimbursable.
- Contact Your Insurer: Call your agent immediately. Provide them with the date and time the damage was discovered.
- Get Professional Estimates: Obtain written estimates from licensed plumbers and restoration companies.
Pro Tip: Be honest and precise. If you knew about a small drip two months ago but didn’t fix it, disclose it. Hiding information can lead to claim denial or policy cancellation for fraud.
Preventing Denials: Maintenance Tips
Since neglect is the primary reason for denial, proactive maintenance is your best defense. Here is a simple checklist to keep your plumbing insurance-friendly:
- Inspect Appliances Annually: Check washing machine hoses for bulges or cracks. Replace rubber hoses with braided stainless steel ones every 5–7 years.
- Monitor Water Pressure: High pressure can stress pipes. Install a pressure gauge; ideal residential pressure is between 40–60 psi.
- Winterize Your Home: Insulate pipes in unheated areas like garages and crawl spaces.
- Install Water Leak Detectors: Smart sensors can alert your phone to moisture before it becomes a flood. Some insurers even offer discounts for having these devices.
FAQ Section
Q1: Does homeowners insurance cover the cost to fix the broken pipe?
A: Typically, no. Most policies cover the resulting water damage to your home and belongings (drywall, flooring, furniture) but exclude the cost of repairing or replacing the defective plumbing component itself. You will likely need to pay a plumber out-of-pocket for the repair.
Q2: Are plumbing leaks typically covered by homeowners insurance if I rent my home?
A: If you are a tenant, your landlord’s insurance covers the structure and their plumbing. However, it does not cover your personal belongings. You need Renters Insurance to cover your clothes, electronics, and furniture if a plumbing leak damages them.
Q3: What is a “water backup endorsement”?
A: This is an optional add-on to your standard policy. It covers damage caused by water backing up through sewers or drains. Since standard policies exclude this, adding this endorsement is highly recommended if you live in an area with older sewer lines.
Q4: How does my deductible apply to water damage claims?
A: You will need to pay your deductible before insurance kicks in. For example, if the damage is $5,000 and your deductible is $1,000, the insurer pays $4,000. Consider whether the repair cost exceeds your deductible significantly; if not, paying out-of-pocket might be smarter to avoid premium hikes.
Q5: Can mold resulting from a plumbing leak be covered?
A: It depends. If the mold results from a covered sudden leak and is addressed quickly, some remediation costs may be covered. However, many policies have strict limits on mold coverage (e.g., capped at $10,000) or exclude it entirely if the moisture was present for more than a certain number of days (often 14–30 days).
Conclusion
So, are plumbing leaks typically covered by homeowners insurance? Yes, but only if they are sudden, accidental, and not the result of neglected maintenance. The key takeaway is that insurance is a safety net for disasters, not a substitute for home upkeep. By understanding the difference between sudden bursts and gradual drips, you can better prepare your home and your finances.
Regularly inspect your plumbing, consider smart leak detectors, and review your policy annually to ensure you have the right endorsements. Don’t wait for a disaster to read the fine print.
Found this guide helpful? Share it with your friends and family on social media to help them protect their homes too!
Leave a Reply