
Are you a commercial property owner or real estate investor feeling the pinch of high taxable income? You might be leaving significant money on the table by depreciating your entire building over 39 years instead of accelerating deductions for specific components. Understanding the nuances of cost segregation plumbing system kitchen hot water heater classifications can unlock immediate cash flow benefits through reduced tax liability.
In this guide, we will break down exactly how these specific assets are treated under current IRS guidelines. We will move beyond basic definitions to provide actionable insights that align with modern tax strategies, ensuring you remain compliant while maximizing your return on investment.
What Is Cost Segregation and Why Does It Matter?
Cost segregation is a strategic tax planning tool that allows real estate owners to accelerate depreciation deductions. Instead of treating an entire commercial building as a single 39-year asset (for non-residential real property), cost segregation identifies components that can be reclassified into shorter recovery periods—typically 5, 7, or 15 years.
This process is not about changing the physical structure; it is about changing how the IRS views the components of that structure. By doing so, investors can leverage bonus depreciation, which has been a powerful tool in recent years, although phase-downs are scheduled in coming years.
The Financial Impact
Consider a $1 million commercial kitchen renovation. If depreciated over 39 years, the annual deduction is roughly $25,641. However, if qualified components are reclassified to 5-year property, the first-year deduction could exceed $200,000 when bonus depreciation is applied. This immediate reduction in taxable income improves liquidity and allows for reinvestment.
How Are Kitchen Hot Water Heaters Classified?
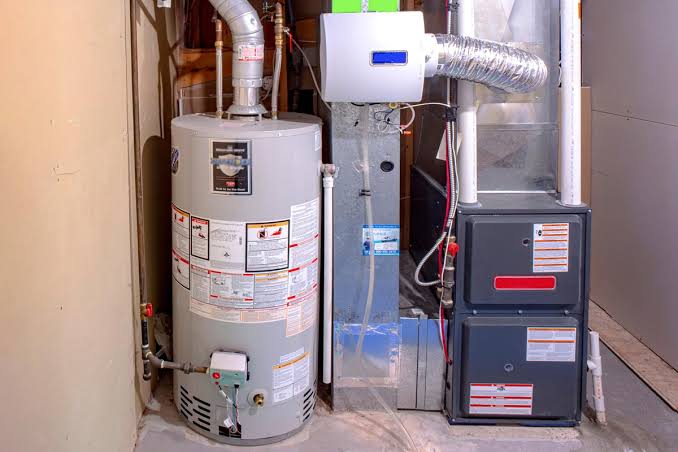
One of the most common questions we receive involves specific mechanical systems. Specifically, how does the IRS view a cost segregation plumbing system kitchen hot water heater?
The classification depends heavily on the function and location of the unit. Generally, there are two primary categories:
- Personal Property (5-Year): If the water heater serves a specific piece of equipment or a distinct area like a commercial kitchen, it is often classified as personal property. This is because it is not essential to the operation of the building itself but rather to the business conducted within it.
- Land Improvement or Building Component (15 or 39-Year): If the water heater provides general hot water to the entire building (e.g., restrooms and break rooms), it may remain part of the building’s structural system.
The “Kitchen” Distinction
For a kitchen hot water heater, the argument for 5-year personal property status is strong. The IRS recognizes that commercial kitchens have unique needs. These units are often dedicated solely to sanitation and food preparation processes. Therefore, they are considered “tangible personal property” rather than structural building components.
Expert Insight: According to industry standards, any asset that can be removed without causing substantial damage to the building structure is a strong candidate for shorter-life depreciation.
Plumbing Systems: Structural vs. Non-Structural
Determining whether a plumbing system qualifies for cost segregation requires a detailed analysis. Not all pipes are created equal in the eyes of the tax code.
General Building Plumbing
Plumbing that is integral to the building’s operation—such as main supply lines, waste lines serving restrooms, and fire suppression systems—is typically classified as 39-year real property. These systems are embedded in walls and floors and are necessary for the building to be habitable.
Specialized Kitchen Plumbing
However, plumbing specifically installed for a commercial kitchen often qualifies for a shorter life. This includes:
- Gas lines dedicated to cooking appliances.
- Water lines connecting directly to dishwashers, ice machines, and prep sinks.
- Drainage systems specifically designed for grease traps and kitchen waste.
When analyzing a cost segregation plumbing system kitchen hot water heater, auditors look at the interconnectivity. If the plumbing serves only the kitchen operations, it supports the case for 5-year or 7-year classification.
| Feature | General Building Plumbing | Commercial Kitchen Plumbing |
|---|---|---|
| Primary Function | Habitability & Safety | Business Operations |
| Typical Life Class | 39 Years | 5 or 7 Years |
| Removability | Difficult/Destructive | Often Accessible/Separate |
| Tax Benefit | Low Annual Deduction | High Initial Deduction |
Step-by-Step Guide to Identifying Qualifying Assets
If you are preparing for a cost segregation study, follow these steps to ensure your kitchen assets are properly documented.
- Review Construction Documents: Gather blueprints, electrical diagrams, and plumbing schematics. Look for separate circuits or lines dedicated to the kitchen area.
- Identify Dedicated Units: Locate water heaters that serve only the kitchen. Note their model numbers and installation dates.
- Document Usage: Keep records showing that these systems are used exclusively for business purposes (food prep, sanitation) rather than general building comfort.
- Consult a Specialist: Engage a qualified cost segregation provider. They will perform an engineering-based analysis to justify the reclassification to the IRS.
Note: Always maintain detailed records. In the event of an audit, documentation is your best defense.
For more background on depreciation methods, you can refer to the general principles outlined on Wikipedia’s page on Depreciation.
Common Mistakes to Avoid
Even seasoned investors make errors when applying cost segregation rules. Here are pitfalls to watch out for:
- Over-Aggressive Classification: Classifying structural walls as personal property will trigger an audit. Stick to clearly defined mechanical and electrical components.
- Ignoring Local Codes: Some local building codes require certain plumbing to be integrated into the structure. Ensure your classification aligns with both IRS rules and local regulations.
- Neglecting Maintenance Records: Poor record-keeping makes it difficult to prove the distinct nature of kitchen-specific assets.
FAQ Section
1. Can I perform cost segregation on an existing building?
Yes. This is called a “look-back” study. You can file Form 3115 to change your accounting method and claim missed depreciation deductions from previous years without amending prior tax returns. This results in a catch-up deduction in the current year.
2. Does the size of the kitchen matter for classification?
The size is less important than the function. Whether it is a small café kitchen or a large industrial facility, if the plumbing and water heating systems are dedicated to food service operations, they likely qualify for shorter depreciation lives.
3. What is the difference between repair and improvement in this context?
A repair maintains the asset’s current condition, while an improvement adds value or extends its life. Cost segregation focuses on improvements. However, distinguishing between the two is crucial for immediate expensing under Section 179 or de minimis safe harbor elections.
4. Will cost segregation trigger an IRS audit?
Not necessarily. While cost segregation studies are scrutinized, having a well-documented, engineering-based study prepared by a qualified professional significantly reduces risk. The IRS has even issued guidance acknowledging the validity of these studies when performed correctly.
5. How long does a cost segregation study take?
Typically, a comprehensive study takes 4 to 6 weeks. This includes data collection, site inspection (if required), engineering analysis, and report generation. Rushed studies may lack the depth needed to withstand IRS scrutiny.
6. Is bonus depreciation still available for these assets?
Yes, but it is phasing down. For property placed in service in 2023, bonus depreciation was 80%. It drops to 60% in 2024, 40% in 2025, and 20% in 2026, before expiring in 2027 unless Congress extends it. Acting sooner rather than later maximizes this benefit.
Conclusion
Optimizing your tax strategy through a cost segregation plumbing system kitchen hot water heater analysis is a smart move for any commercial real estate investor. By correctly classifying these assets, you can shift from a 39-year depreciation schedule to a 5-year schedule, unlocking substantial cash flow in the early years of ownership.
Remember, the key lies in accurate identification and thorough documentation. Do not let generic depreciation rules dictate your tax liability. Take control of your assets and ensure every eligible component works harder for your bottom line.
Found this guide helpful? Share it with your fellow investors on LinkedIn or Twitter to help them uncover hidden tax savings too!
Leave a Reply